Willkommen. Schön, sind Sie da!
0
IHR WARENKORB IST AKTUELL LEER.
Haben Sie noch nichts passendes gefunden? Stöbern Sie durch unser komplettes Sortiment.
Oder melden Sie sich an bzw. registrieren Sie sich.
Ihre Vorteile
- Kostenlose Lieferung
- Kauf auf Rechnung
- Ex Libris Tiefpreis
- Filiallieferung und 650+ Abholorte
- Rabatt-Bons als Club-Mitglied
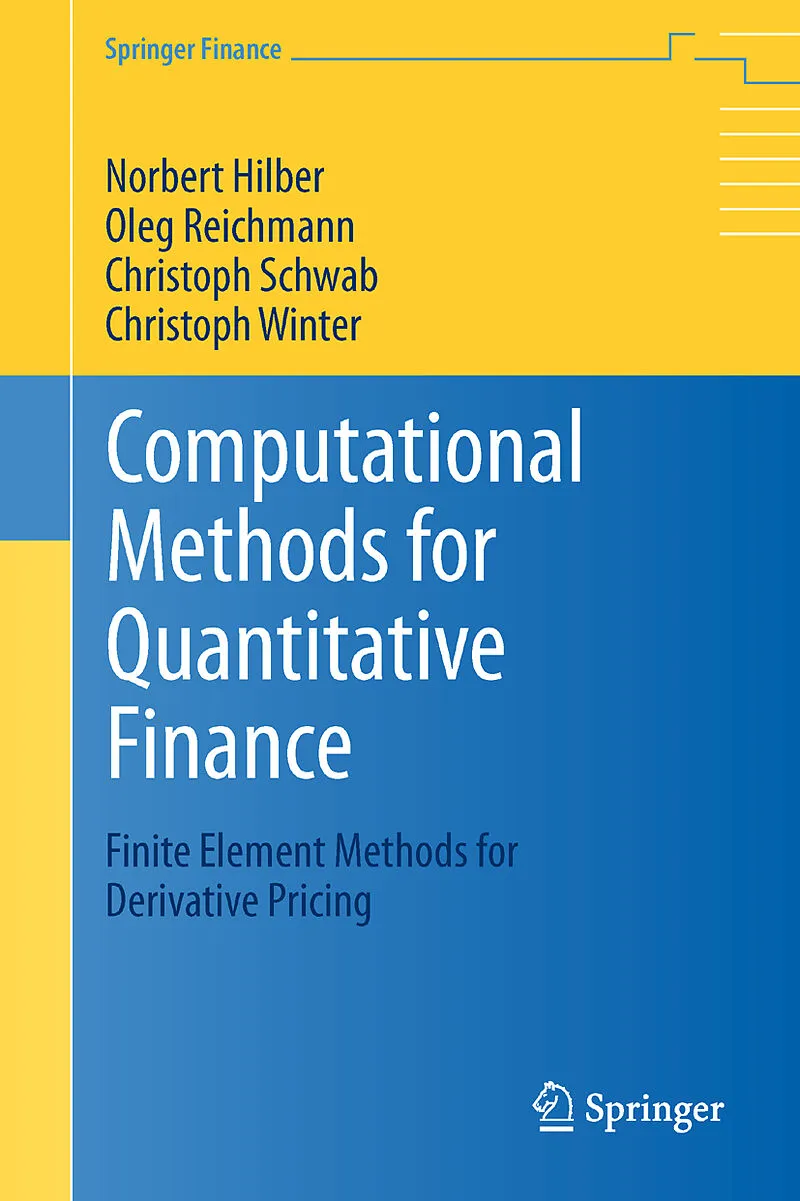
Computational Methods for Quantitative Finance
Beschreibung
This book introduces algorithms for fast, accurate pricing of derivative contracts. These are developed in classical Black-Scholes markets, and extended to models based on multiscale stochastic volatility, to Lévy, additive and classes of Feller processes. Man...Format auswählen
- Fester EinbandCHF 131.60
- E-Book (pdf)CHF 89.90
- Kartonierter EinbandCHF 102.00
TIEFPREIS
CHF131.60
Print on Demand - Exemplar wird für Sie besorgt.
Kostenlose Lieferung